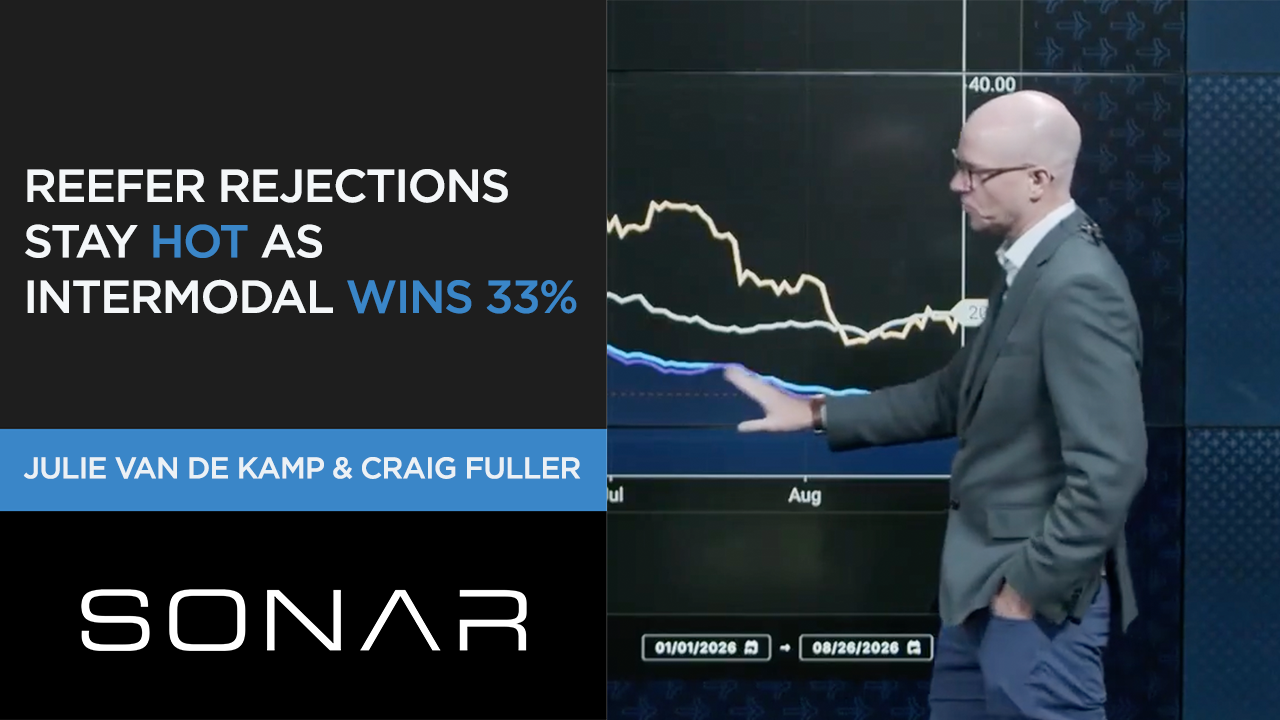
Reefer tender rejections remain stuck at 20% to 20.5% even as dry van and flatbed rejection rates ease, while a 33% intermodal cost-savings gap is pulling record volumes of freight off the road and onto rail, according to FreightWaves SONAR data reviewed during a recent SONAR Daily Update with FreightWaves' Craig Fuller and Julie Van de Kamp.
Reefer Rejections Hold Steady While Other Modes Ease
Refrigerated tender rejections are bucking a broader softening trend across truckload modes, holding steady at 20% to 20.5% even as van and flatbed rejection rates ease, according to FreightWaves SONAR data. The persistence is partly seasonal — hot summer temperatures drive demand for temperature-controlled capacity — but Fuller and Van de Kamp identified a structural factor that may matter more to carriers and shippers: refrigerated trailers cannot easily convert to intermodal. Unlike dry van freight, reefer loads require purpose-built refrigerated containers that must run continuously, making mode substitution largely unavailable as a pressure valve.
"Refrigerated is the least fungible mode with intermodal," Fuller said.
Intermodal's 33% Savings Gap Drives Record Rail Volumes
That intermodal pressure valve, meanwhile, is wide open for dry freight. The intermodal contract savings index — which measures the cost gap between intermodal and over-the-road trucking — is running 33% above trucking costs, the highest level in at least three years, according to FreightWaves. Van de Kamp pointed directly to that figure as the driver of record intermodal volumes.
"33% — I think that's your answer on why intermodal is so strong right now," she said.
Fuller noted that the modest recent dip in the savings index likely reflects spot truck rates easing slightly rather than any move in intermodal pricing — a dynamic that could narrow the gap if trucking softens further heading into fall. Van de Kamp added: "Intermodal is not getting cheaper. It's just not getting more expensive."
Total outbound rail container volumes are running significantly above the prior three years on a seasonally adjusted basis, with SONAR data showing the current year's volume trajectory continuing upward alongside the widening cost-savings index, according to FreightWaves.
| Mode / Metric | Current Status | Driver Cited by FreightWaves |
|---|---|---|
| Reefer tender rejections | Steady at 20%–20.5% | Summer heat + no intermodal substitution |
| Van and flatbed rejections | Easing | Broader softening (van); construction seasonality (flatbed) |
| Intermodal contract savings index | 33% above over-the-road trucking | Three-year high cost gap |
| Outbound rail container volumes | Above prior three years, seasonally adjusted | Widening savings index |
Flatbed Eases as Construction Season Winds Down
Flatbed rejections, by contrast, have fallen sharply from their spring highs. Van de Kamp attributed the pullback to construction seasonality: building materials move heavily in the first half of the year before summer heat slows construction activity, particularly in northern markets where the building season can be limited to roughly 10 months. With that demand cycle winding down, flatbed capacity has loosened considerably, according to FreightWaves.
Cross-Border Rail Watched for Tariff Shifts
On the cross-border rail front, Fuller flagged early data on Canada-to-U.S. and U.S.-to-Canada outbound rail container volumes as a potential leading indicator for tariff-related trade shifts, though both analysts said it is too early to draw conclusions. Van de Kamp noted that Canadian rail volumes in bulk commodities — metals and mining in particular — have been lagging U.S. levels for some time, predating the current tariff environment. Fuller added that Mexican rail volumes remain relatively strong but represent only a small share of overall North American rail activity. Both said they will continue tracking cross-border flows for signs of tariff impact in the weeks ahead.
Watch List
- Labor Day mode conversion: FreightWaves' SONAR Daily Update framed the intermodal shift and reefer tightness as the key dynamics heading into the Labor Day holiday period.
- Fall trucking softness: If spot truck rates ease further, the intermodal savings gap could narrow, according to Fuller.
- Cross-border tariff signals: U.S.-Canada and U.S.-Mexico outbound rail container volume data are being monitored as potential early indicators of tariff-driven trade shifts, but current data are inconclusive.
Sources: