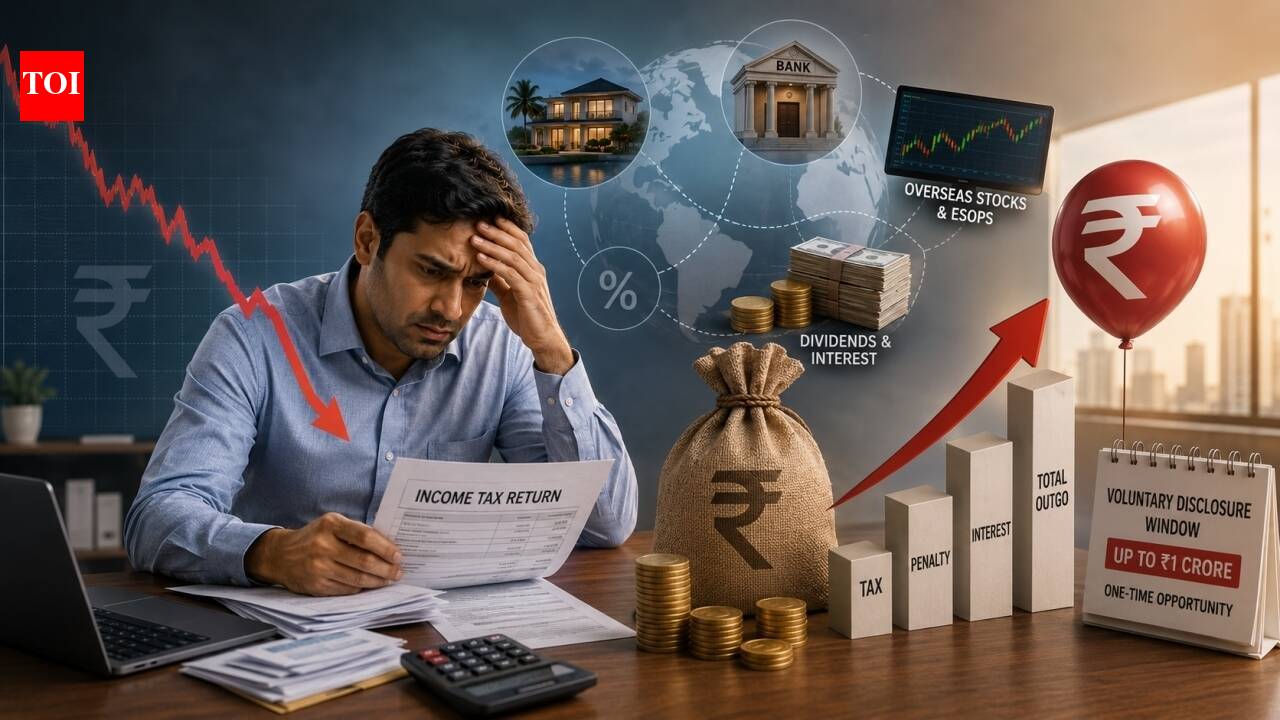
Weaker rupee, which has declined 14-33% against the US dollar over three to seven years, may push foreign asset holdings above the Rs 1 crore ceiling of the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (FAST-DS), potentially costing taxpayers the lower 60% tax-and-penalty disclosure window and exposing them to steeper income tax bills, according to a Business-Today report.
The Income Tax Department opened a one-time voluntary disclosure window on August 16, allowing individuals to regularise overseas shares, properties, ESOPs, dividends, interest and other such assets by paying 60% in tax and penalty, for amounts up to Rs 1 crore. The rules specify March 31, 2026 as the exchange-rate date for converting dollar-denominated assets into Indian rupees, but do not clearly state which date should be used for converting foreign income. With the rupee's decline, many taxpayers could find their holdings cross the Rs 1 crore threshold if March 31 is used for currency conversion — the reason for worry about a higher tax outgo, the report said.
Rupee decline and the valuation trap
The scheme's valuation provisions can lead to unexpected outcomes. For several categories of foreign assets, the value is generally determined as the higher of acquisition cost or market value. "If an overseas asset bought for 5.25 crore is today worth only 3 crore, its value for the scheme may still remain 5.25 crore. The taxpayer could therefore fall outside the scheme," said advocate Priyanshi Chokshi in the report.
| Key figure | Value |
|---|---|
| Rupee decline over 3-7 years | 14-33% |
| FAST-DS tax and penalty | 60% |
| FAST-DS asset ceiling | Rs 1 crore |
| Maximum declarable assets (LRS/returning NRI) | Rs 5 crore |
| Potential saving via updated-return route | Rs 30-40 lakh |
| Tax difference between FAST-DS and updated return | Up to 40% |
Two expert views on the conversion date
The correct conversion date is contested. Ved Jain, former president of the Institute of Chartered Accountants of India (ICAI), said that under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Rules, 2015, the valuation date for an undisclosed foreign asset is the date on which the asset comes to the assessing officer's notice. He told ET that the scheme therefore takes March 31, 2026 as the valuation date for income as well.
Chartered accountant Ashish Karundia takes a different view. In the Business-Today report, he said:
"Undisclosed foreign income means income from a source outside India that was chargeable to tax in India but not offered to tax under the 1961 I-T law. The starting point is to determine how that income would have been computed and offered to tax under existing law. This requires reference to the I-T Rules, 1962, including Rule 115, which prescribes conversion of foreign-currency income. Thus, the applicable rate is the one that prevailed during the year income was earned."
Updated return and FAST-DS: A risky arbitrage
Taxpayers with undisclosed income of over Rs 1 crore — such as Rs 2 crore — are exploring the use of both an updated return and FAST-DS. Because the tax payable through an updated return could be higher, an assessee may potentially save Rs 30-40 lakh. Chartered accountant Harshal Bhuta said the Rs 1 crore ceiling has created an incentive to divide undisclosed income between the two, by declaring the amount above Rs 1 crore through an updated return and using FAST-DS for the remaining amount.
Although this strategy may appear beneficial because of a tax difference of up to 40%, as well as immunity from penalty and prosecution, Bhuta warned that a FAST-DS declaration could be considered void if authorities find misrepresentation or suppression of facts. This could leave the taxpayer without recourse later.
What this means for finance executives
For CFOs, treasury directors and investors holding overseas shares, ESOPs or dividends, the rupee's depreciation directly changes the rupee-denominated value of foreign assets and, in turn, tax compliance thresholds. The scheme permits declaration of foreign assets worth up to Rs 5 crore acquired using tax-paid money by residents under the liberalised remittance scheme, as well as by returning NRIs who failed to disclose foreign accounts. The report noted the scheme is intended to give assessees an opportunity to rectify genuine errors, but the valuation provisions can lead to unexpected outcomes — a point that underscores the need to verify which conversion date applies before the window closes.
Sources: