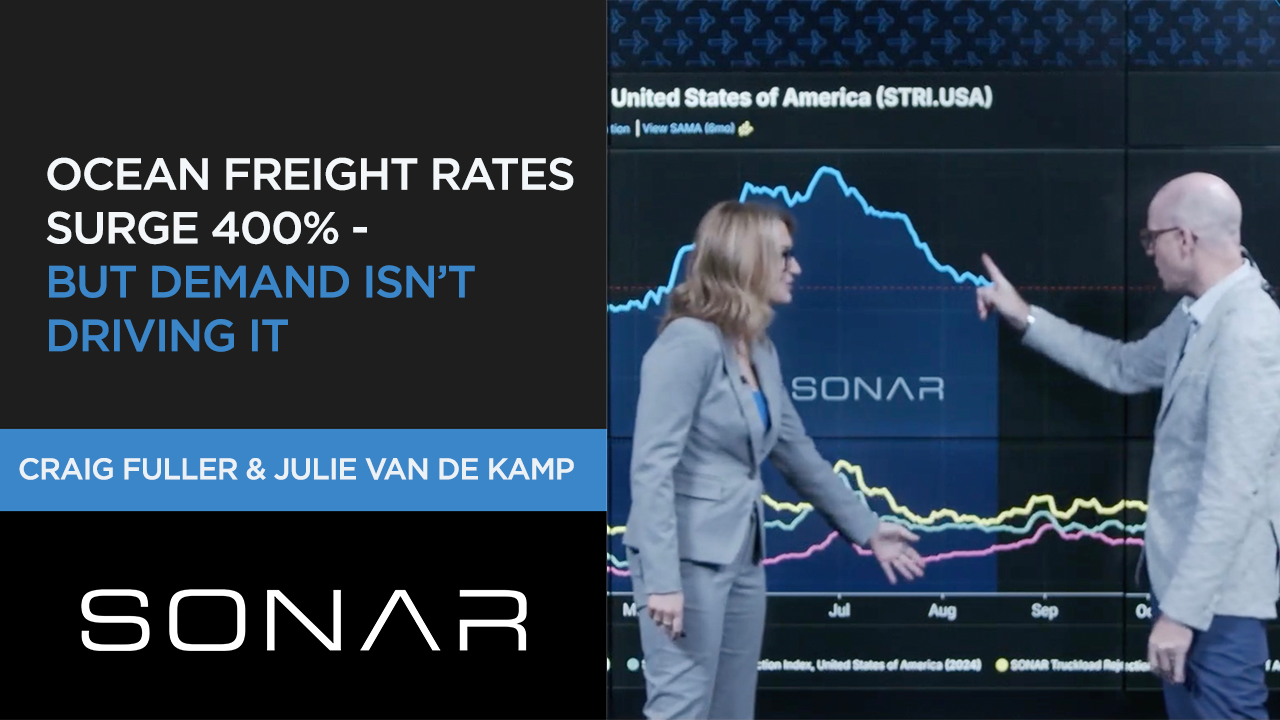
Ocean freight spot rates have skyrocketed by over 400%, according to FreightWaves SONAR data, even as cargo volumes out of China to the U.S. are down roughly 1%. The China-to-U.S. East Coast spot rate has reached $9,400 per TEU, with West Coast rates also posting sharp gains — particularly since early August, according to the FreightWaves SONAR update. The disconnect between flat-to-negative demand and surging prices points squarely at supply-side management by ocean carriers, not a freight boom.
Capacity Concentration Gives Carriers Pricing Power
The top 10 ocean container lines control approximately 90% of global container shipping capacity — a market concentration that dwarfs OPEC's roughly 36% share of global oil supply, according to the FreightWaves analysis. Crucially, those carriers are exempt from U.S. antitrust law, meaning they can legally coordinate sailing schedules and pull capacity from the market through blank sailings and slow steaming, driving rates higher without running afoul of regulators.
In the FreightWaves SONAR update, Julie Van de Kamp explained the dynamic: "While they may not be collaborating on price, they're actually collaborating on capacity in ways that give them pricing power. And that is really important. And I think it's why you see U.S. consumers and U.S. businesses having to pay really high container rates."
Rate Benchmarks: East Coast at $9,400 per TEU
| Metric | Value |
|---|---|
| China-to-U.S. East Coast spot rate | $9,400 per TEU |
| China export volumes to U.S. | Down ~1% |
| Top 10 carriers' share of global container capacity | ~90% |
| OPEC share of global oil supply | ~36% |
| Yang Ming profit surge (latest report) | +482% |
| Spot rates after 2016 Hanjin Shipping collapse | ~$800 per TEU |
Carriers are also pointing to environmental and weather factors to justify capacity restraint. El Niño has warmed the Pacific Ocean, increasing typhoon activity, while drier-than-normal conditions have lowered water levels in the Panama Canal, further tightening effective vessel capacity, according to the FreightWaves update. Van de Kamp framed the carriers' posture bluntly: "No crisis left untouched."
Yang Ming's 482% Profit Surge Spotlights Carrier Strategy
Taiwan-based carrier Yang Ming's latest earnings report underscored the dynamic, reporting a 482% profit surge and citing an early peak season and firmer freight rates. The carrier also flagged trade policy uncertainty, geopolitical disruption in the Red Sea, and expectations that vessel supply additions will outpace demand growth — factors that could introduce volatility heading into the fourth quarter.
The current rate environment mirrors the industry shift after the 2016 collapse of Hanjin Shipping, when spot rates bottomed around $800 per TEU and carriers held no pricing power, according to the report. Since then, the industry has moved from fighting for market share to defending profitability. "It's no longer about he who has the most ships win," Van de Kamp said. "It's who has the highest profitability."
Shippers Should Brace for Q4 Volatility
For shippers planning fourth-quarter freight budgets, Craig Fuller of FreightWaves advised expecting continued turbulence, according to the report. Port delays are already increasing, with carriers attributing them to weather disruptions. With blank sailings keeping capacity tight and carriers motivated to sustain elevated rates, shippers should anticipate volatility in both rates and available capacity through the end of the year.
The FreightWaves update also promoted the upcoming Brokerage Compliance Symposium, held the day before F3, covering fraud exposure, carrier liability, FMCSA rules, cargo theft, and insurance gaps — a sign of the shift toward a more regulated operating environment.
Watch List
- Whether Yang Ming's warning that vessel supply additions will outpace demand growth dampens rate momentum in Q4
- Trade policy uncertainty and geopolitical disruption in the Red Sea, flagged by Yang Ming as volatility risks
- Panama Canal water levels and El Niño-driven typhoon activity, both cited as capacity constraints
- How long carriers sustain blank sailings to defend elevated rate levels through year-end
Sources: