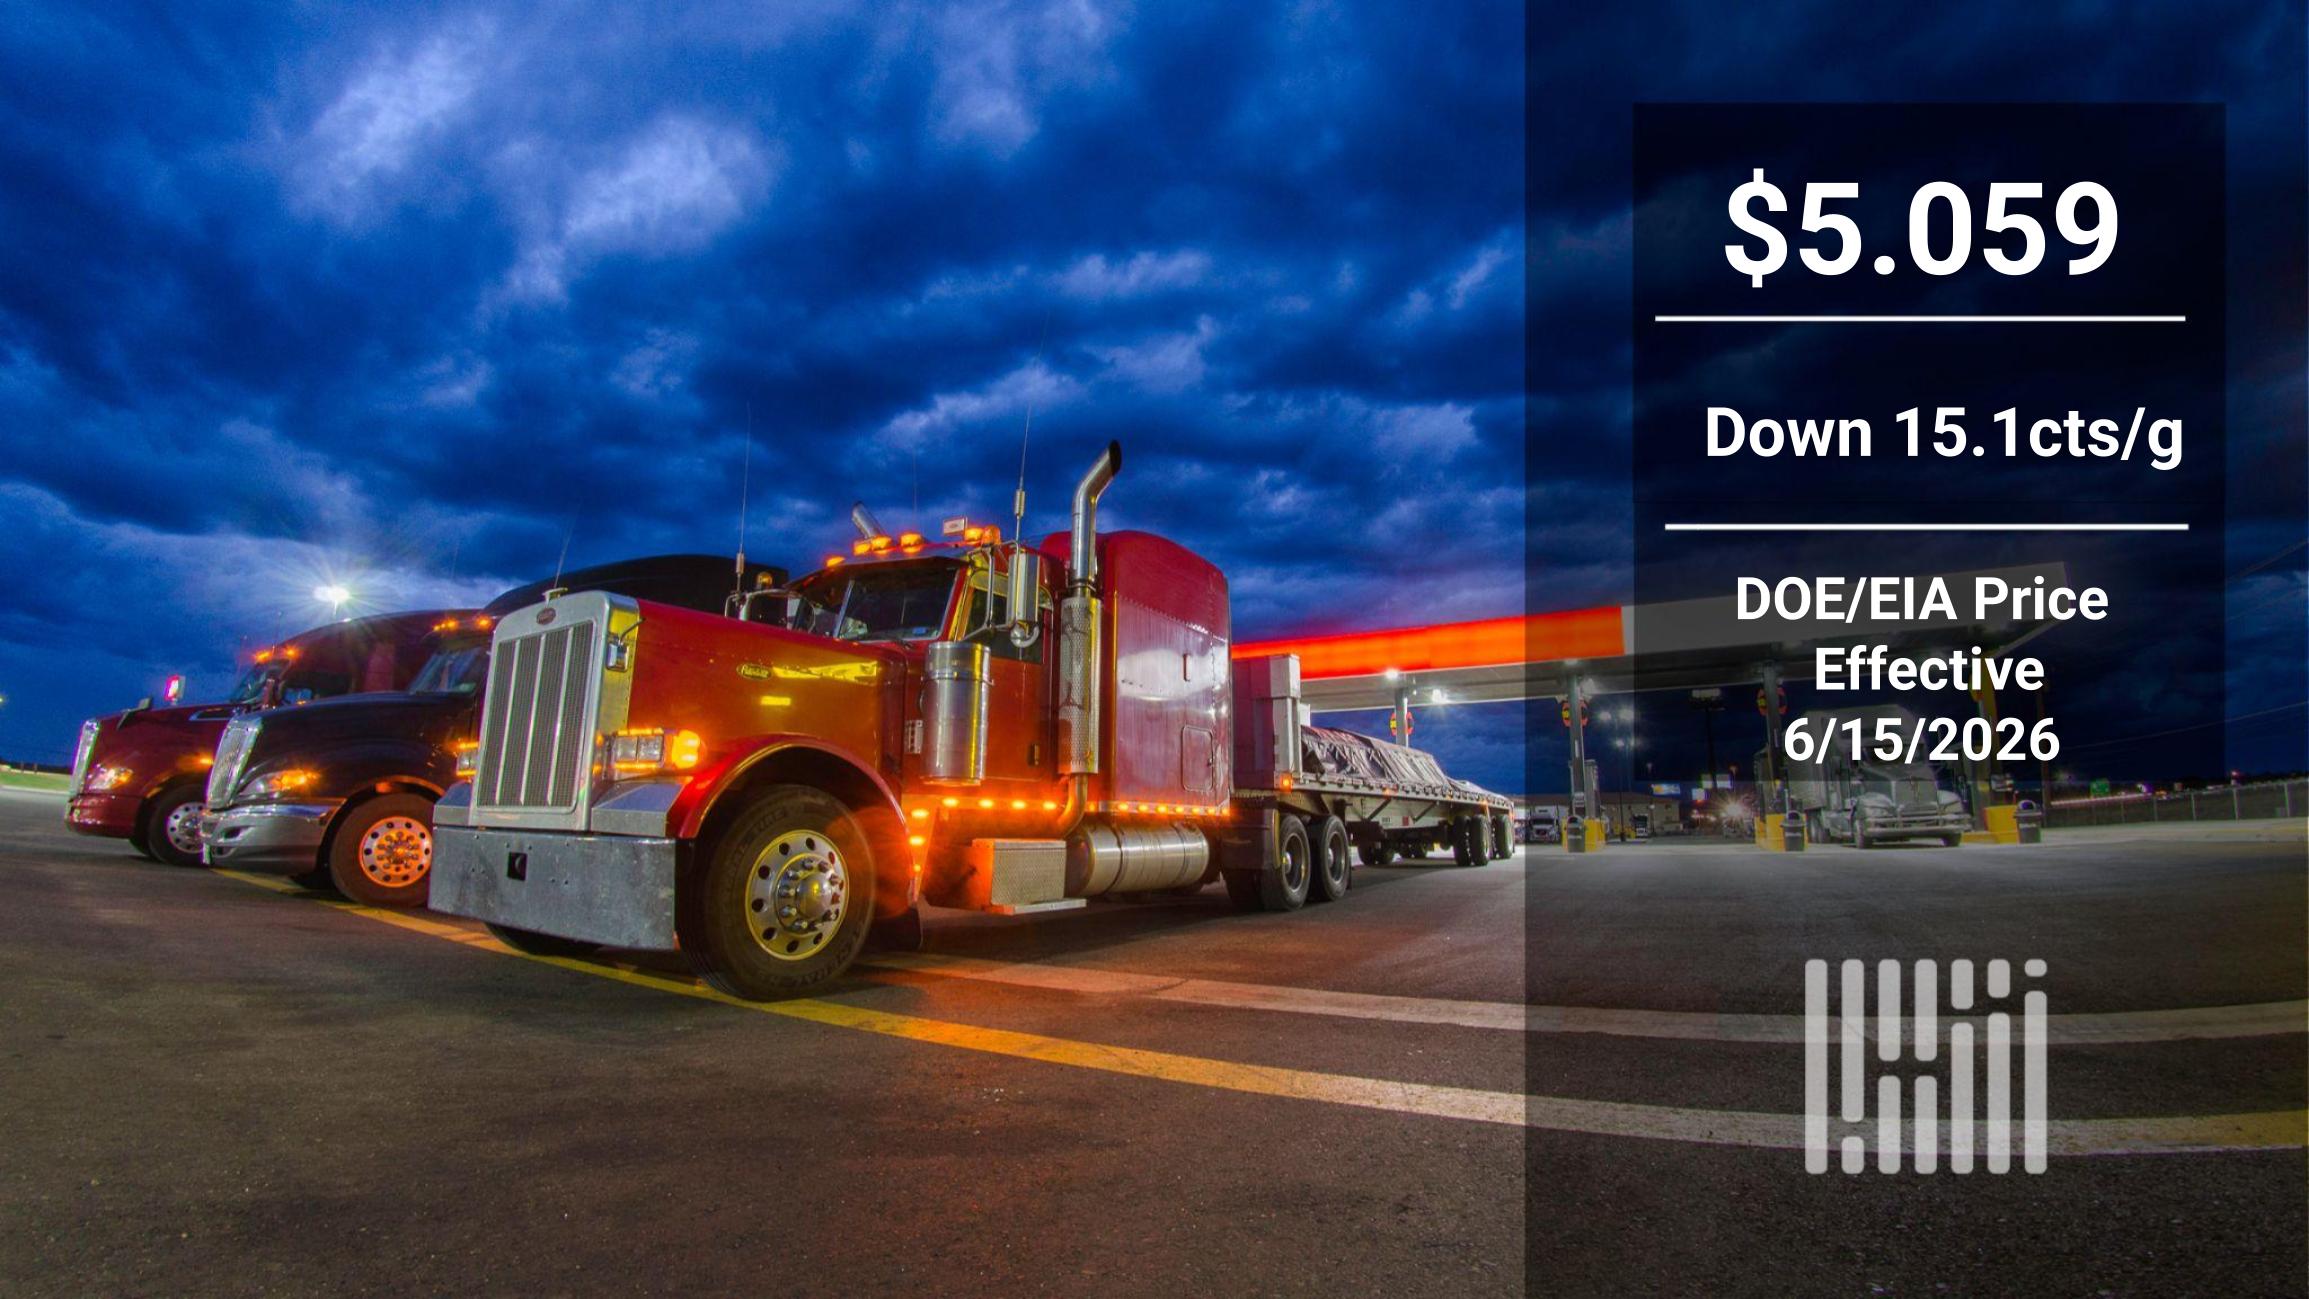
The International Energy Agency's monthly report released Wednesday offers dual interpretations for oil price direction following the U.S.-Iran peace deal, even as diesel prices continue their sharp decline, according to FreightWaves. The weekly DOE/EIA average retail diesel price fell 15.1 cents to $5.059 per gallon, the lowest since March 16, 2026.
Price Decline Accelerates
Ultra low sulfur diesel (ULSD) on the CME settled at $3.1702 per gallon on Tuesday, down 44.24 cents in four trading days. That settlement is $1.5138 below the March 20 post-war high of $4.6084. Before the conflict began on March 2, ULSD settled at $2.596 per gallon.
IEA Report: Bullish and Bearish Signals
The IEA does not predict prices, but this month's report supports both outlooks. Global supply in 2026 is expected to average a decline of 3.9 million barrels per day (b/d) to 102.4 million b/d compared to 2025. However, short-term disruption is severe: May production fell to 94.5 million b/d, down 13.6 million b/d from pre-war levels.
Demand is also falling, but less dramatically. Second-quarter demand is estimated down about 5 million b/d (4.8%) year-over-year "in the face of higher fuel prices and disruptions to product availability," the agency said. Full-year demand is set to decline an average of 1.1 million b/d, with the forecast raised by 700,000 b/d from a month ago.
Supply and Demand Balance
The IEA wrote: "Deep cuts to consumption have spread beyond the sectors and regions that were initially the most heavily impacted." Reported data for April (-4.6 million b/d y-o-y) and May (-5.4 million b/d) show plunging demand across almost all product categories and regions. Asia and the Middle East are most affected, with Chinese, Korean, and Japanese deliveries especially hard-hit.
Despite demand declines, supply is falling more, suggesting potential upward pressure once buffers are exhausted.
Role of 'Buffers' in Price Containment
The IEA has used the term "buffers" to describe factors that limited oil price increases despite the loss of almost 20% of world supply at times due to the Strait of Hormuz shutdown. Brent crude settled at $78.96 per barrel on Tuesday, down from a post-war high of $118.35 on March 31 but above the pre-war level of $72.48 on February 27.
Key Price Comparisons
| Product/Index | Pre-War (Feb 27) | Post-War Peak | Current (June 16) | Change from Peak |
|---|---|---|---|---|
| Retail Diesel (DOE/EIA) | $3.897/gal (Mar 2) | $5.071 (Mar 16) | $5.059 | -$0.012 |
| ULSD (CME) | $2.596/gal | $4.6084 (Mar 20) | $3.1702 | -$1.4382 |
| Brent Crude | $72.48/bbl | $118.35 (Mar 31) | $78.96 | -$39.39 |
Outlook and Consumer Impact
The IEA's shorter-term outlook is most concerning for consumers. With supply falling more than demand, the buffers that kept prices from spiking further may soon be exhausted, potentially leading to a post-peace surge. However, the peace deal has already triggered a sharp decline in diesel and crude prices, and markets remain uncertain. Traders and procurement teams should watch for upcoming IEA data on inventory levels and OPEC+ compliance as the market digests the IEA's mixed signals.
Sources: