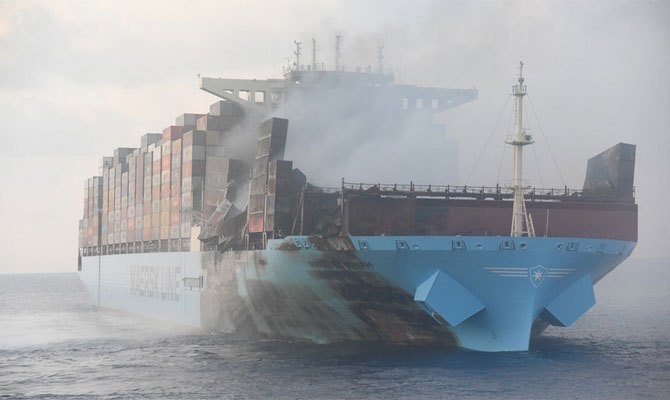
Mediterranean Shipping Co. (MSC) has joined other global container lines in returning to the southern Red Sea despite a resumption of attacks on vessels by Houthi rebels based in Yemen, according to FreightWaves. The move comes as trans-Pacific ocean spot rates remain elevated and are still climbing, driven by shipper anxiety over possible U.S. tariff increases, carrier capacity reductions, and congestion at major ports in China. The latest Baltic Index from SONAR data contributor Freightos shows Asia-U.S. West Coast prices up 1% to $6,826 per forty-foot equivalent unit (FEU), and Asia-U.S. East Coast prices 2% higher at $9,576 per FEU.
Red Sea return
FreightWaves reported that Mediterranean Shipping Co. has joined other global liners in a return to the southern Red Sea despite the resumption of Houthi attacks. Freightos analyst Judah Levine wrote in a note to clients:
These steps are sparking some optimism that we are seeing the start of a gradual return to normal levels of container traffic through the waterway.
The article notes that while unfounded fears of higher tariffs helped drive unexpected demand from anxious shippers this summer, other geopolitical intrigue is keeping the container market on edge.
Rate snapshot
According to the latest Baltic Index from SONAR data contributor Freightos:
| Trade lane | Index price | Change |
|---|---|---|
| Asia–U.S. West Coast | $6,826 per FEU | +1% |
| Asia–U.S. East Coast | $9,576 per FEU | +2% |
FreightWaves also reported that West Coast spot rates ticked up to $7,600 per FEU this week, a level last seen in early July — roughly $5,000 higher than before the peak season began in late May. East Coast prices have held near $9,000 and climbed another $800 in August.
What's supporting trans-Pacific rates
FreightWaves reported that reductions in capacity by carriers and congestion at major ports in China have helped support elevated rates on the trans-Pacific. Levine said a trimming of transits by the Panama Canal — and carrier canal surcharges — "could put upward pressure on rates for some Asia-U.S. East Coast services."
Levine also linked the sustained demand to tariff policy: "The concern that the White House would substantially increase tariff levels to close July may have been one factor driving the early start to peak season demand and spiking container rates back in June," he said. "That tariffs remained about level, and that the window until possibly higher tariffs remains open, may help explain the current, surprising, sustained container demand and peak rate levels on the trans-Pacific."
Implications for shippers and operators
Shippers should expect continued high trans-Pacific costs while peak-season demand holds and capacity remains constrained, based on the rate data in FreightWaves' report. The return of MSC and other liners to the southern Red Sea could signal a gradual normalization of container traffic through that waterway, which Levine described as a step toward normal levels. However, the broader geopolitical picture remains tense: FreightWaves reported that the impasse over control of the Strait of Hormuz is about to enter its seventh month, and the United States is trying to tighten economic sanctions on countries doing business with Iran. Analysts cited in the article said it is unlikely Beijing — Iran's top customer for crude oil — would support the penalties, while others point to the Trump administration's changing approach as validating Tehran's position to wait out the remainder of the U.S. president's term.
Watch list
- Strait of Hormuz impasse entering its seventh month
- U.S. efforts to tighten economic sanctions on countries doing business with Iran
- U.S.-China trade relations and the possibility of further tariff increases
- Panama Canal transit reductions and carrier surcharges
- Carrier capacity reductions and congestion at major ports in China
- Further moves by container lines returning to the southern Red Sea
Sources: