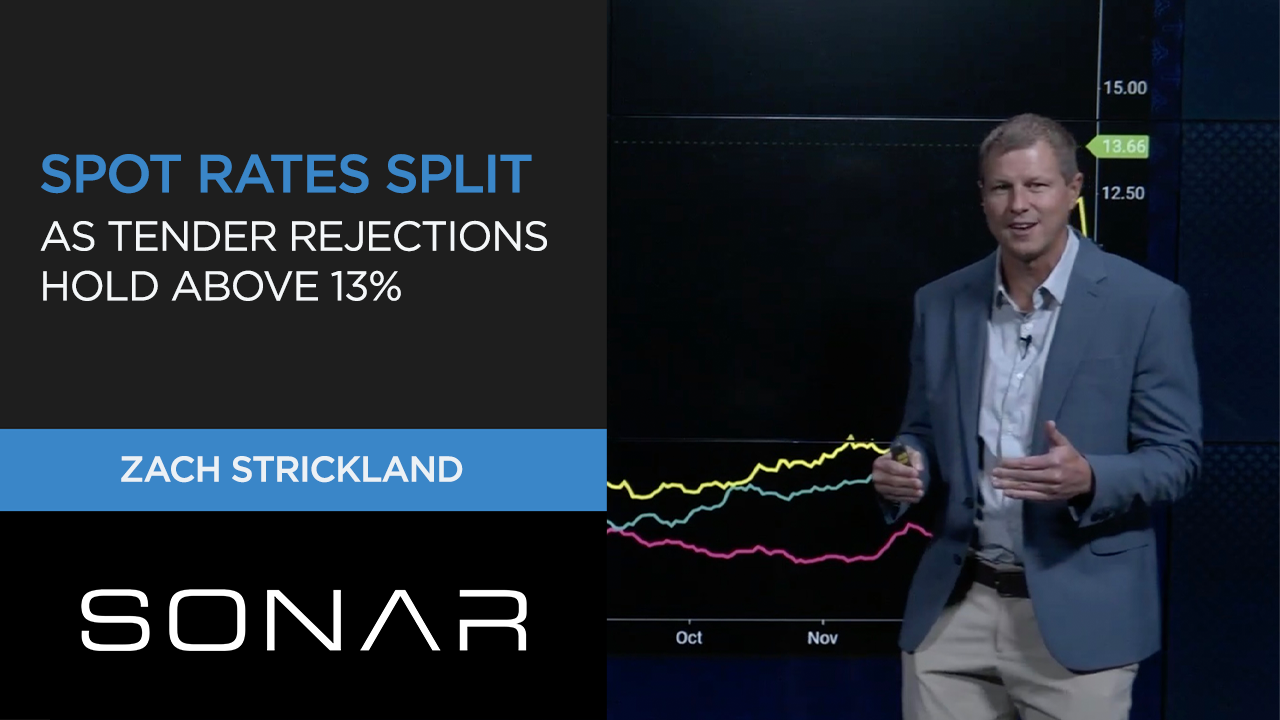
Freight market conditions are stronger than the surface-level softness suggests, with the national tender rejection index at roughly 13.5% — a level that never appeared at any point during all of 2024, even during last year's peak season, according to FreightWaves' SONAR update.
The apparent cooling is a seasonal pattern, not a structural shift, FreightWaves reported on FreightWaves Today. SONAR data reviewed live on the broadcast shows a 34% cost discount between intermodal contract rates and truckload contract rates, pushing shippers toward rail as peak season approaches.
The 34% Rail Discount Is Reshaping Mode Choice
Truckload contract rates have risen 7.5% over the past three months, while intermodal contract rates have remained essentially flat, up just 0.6% over the same period, according to SONAR. That spread is fueling volume gains for domestic intermodal operators and the railroads that support them, and supports rail's growing market share.
"Why would you not take advantage of that?" — Craig Fuller, on the door-to-door pricing gap between train and truck
Fuller said the 34% discount reflects door-to-door pricing for putting freight on a train versus a truck. Julie Van de Kamp added that the mode conversion opportunity is especially compelling in the eastern half of the U.S., where truckload capacity has been the tightest and where the bulk of the intermodal volume increases are concentrated.
Unlike past constraints, the eastern U.S. concentration makes recovery easier, Fuller said: "Unlike past crunches, like if you go back during COVID where you had that massive intermodal crunch because you couldn't get chassis… the fact that these are on the eastern half means that the railroads and the IMCs can balance their networks so much easier."
Rejection Index at 13.5%: Not the Softness It Looks Like
The national tender rejection index currently sits at approximately 13.5%, a level that never appeared at any point during all of 2024, even during last year's peak season. Van de Kamp emphasized that while 13.5% may feel modest relative to the elevated readings of recent months, it represents a significant premium over where the market stood in prior years.
SONAR's historical data shows tender rejections peaked around the July 4th holiday weekend, as they have consistently across multiple years. Fuller said he expects a pickup beginning in the last week of August heading into Labor Day, followed by peak-season tightening in mid-October through early November as retailers push product into brick-and-mortar supply chains ahead of Black Friday.
Rates and Volumes: Spot at $3.34 and Volume Consolidation
Spot rates at $3.34 per mile are 21% above last year's levels and still within range of the all-time record Fuller cited at roughly $3.55 per mile set in late 2021, according to the SONAR update. Outbound tender volumes have pulled back from a Memorial Day surge but are now consolidating, running above 2024 and 2025 comparison lines and roughly in line with the same period in 2023.
A major mall operator Fuller spoke with the morning of the broadcast described consumer activity as "really robust," which he said supports a constructive outlook for the remainder of the year.
| Metric | Current reading | What it means |
|---|---|---|
| National tender rejection index | ~13.5% | Higher than any reading during all of 2024, including last year's peak season |
| Truckload contract rates | +7.5% in three months | Outpacing intermodal, widening the price gap |
| Intermodal contract rates | +0.6% in three months | Essentially flat, making rail cheaper by comparison |
| Intermodal vs. truckload contract spread | 34% discount | Door-to-door train pricing versus truck |
| Spot rates | $3.34 per mile | 21% above last year; record range ~$3.55 per mile (late 2021) |
| Outbound tender volumes | Consolidating | Above 2024 and 2025 comparison lines, roughly in line with 2023 |
| Intermodal API coverage | 2,000+ lanes | New SONAR API released this week |
What Shippers, Forwarders and 3PLs Should Watch
For shippers, the mode conversion opportunity is especially compelling in the eastern half of the U.S., where truckload capacity has been tightest, Van de Kamp said. FreightWaves' SONAR platform released a new intermodal API this week covering rates across more than 2,000 intermodal lanes, with broader UI availability described as coming soon. Van de Kamp called the timing ideal given the surge in shipper interest in mode conversion.
Fuller flagged JB Hunt — which he described as the largest domestic intermodal operator — along with Hub Group, Schneider, and Knight-Swift as companies positioned to benefit from the current intermodal pricing environment.
Operators should treat the current dip as normal seasonal behavior rather than a structural softening, Fuller said. The expected pickup beginning in the last week of August heading into Labor Day, followed by mid-October to early-November peak-season tightening, gives forwarders and 3PLs a window to act on the 34% intermodal discount identified in SONAR data.
Watch List
- Tender rejection index trajectory through the last week of August, when Fuller expects a pickup ahead of Labor Day.
- Peak-season tightening window from mid-October through early November, driven by brick-and-mortar retail restocking ahead of Black Friday.
- Broader UI availability of SONAR's new intermodal API, described as coming soon after this week's 2,000-lane release.
- Whether the modal shift from truck to intermodal accelerates in the eastern half of the U.S., where the bulk of intermodal volume increases are concentrated.
- Truckload contract rate momentum — up 7.5% in three months — versus essentially flat intermodal contract rates.
Sources: